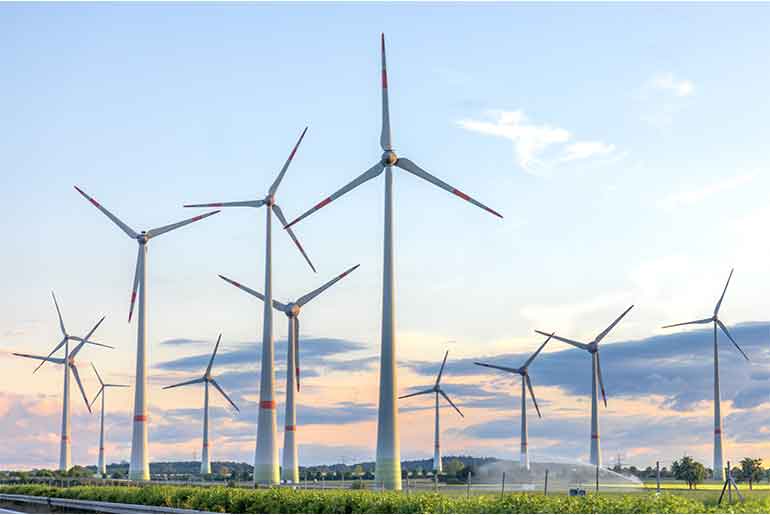
US wind turbine firm orders reached 2.8 GW in the second quarter of 2026, marking their highest level since the fourth quarter of 2023. According to Wood Mackenzie’s US Wind Energy Monitor Q3 report, the increase was primarily driven by developers seeking to meet federal tax credit deadlines and advance projects targeted for completion by 2030.
The US added 5 GW of onshore wind capacity during the quarter, largely supported by the commissioning of the 3.65 GW SunZia project in New Mexico. The project is the largest wind energy development in the country to date.
Developers accelerated turbine procurement to comply with tax policy deadlines. With tax credits for qualifying wind projects scheduled to expire at the end of the decade, developers placed turbine orders before July 4 to meet the applicable construction-start requirements.
Tyler Gifford, an analyst at Wood Mackenzie, said policy remains the most influential factor affecting wind installations. Developers are prioritising projects that can become operational by 2030, supporting a stable five-year outlook for onshore wind capacity additions.
Wood Mackenzie expects the US to add 39 GW of new onshore wind capacity by 2030. More than half of the project pipeline scheduled for 2026–2028 is already under construction or operational.
Texas is projected to remain the largest onshore wind market over the next five years, accounting for nearly a quarter of expected capacity additions. However, the western region is expected to lead new capacity growth, with Colorado, New Mexico and Wyoming projected to be the three largest markets.
Wood Mackenzie also revised its September 2026 repowering forecast downward by 1 GW quarter-on-quarter, reflecting fewer equipment orders for repowering projects than previously anticipated. The report noted that the 80/20 tax credit mechanism continues to support wind fleet renewal, while decommissioning activities are creating additional repowering opportunities.
Wood Mackenzie maintained its five-year outlook for US offshore wind capacity at 5 GW, with all projected additions expected to become operational by the fourth quarter of 2027. Construction activities continue across turbine installation, foundation development and testing.
Meanwhile, offshore wind lease relinquishments continued through September, taking cumulative federal buyouts close to $4 billion, according to the report.
Wood Mackenzie warned that the lack of stable, long-term policy support could lead offshore wind developers and financiers to shift their focus away from new US projects beyond 2027.
Proposed building code requirements from the American Society of Civil Engineers (ASCE) could increase wind project costs across significant parts of the US. The proposed ASCE 7-28 guidance is expected to introduce additional design requirements for wind turbines in tornado-prone areas, depending on specified tornado wind-speed thresholds and structural exposure limits.
Despite policy uncertainty, Wood Mackenzie expects wind energy to remain an important contributor to the US electricity generation mix through 2030. Gifford said the project pipeline remains well positioned in the near term, with developers focused on construction execution before the tax credit window closes.
 Electrify your feed! Click here to join our Whatsapp group and to get the latest updates, expert insights, and innovations driving India’s energy storage revolution.